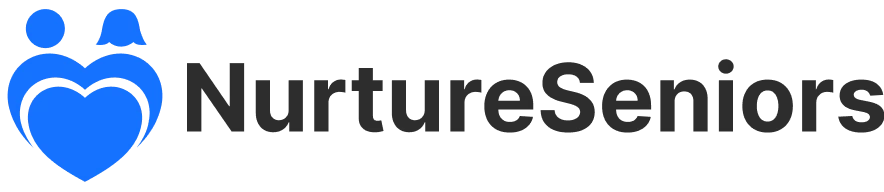
This guide explains how Lifetime Benefits Solutions help organizations and households build durable value over time. It provides objective background on the meaning of lifetime-oriented planning, the role of risk management, and how structured supplier and cost considerations shape decisions. You’ll also find expert evaluation criteria, practical requirements, and FAQs to support informed implementation.
Lifetime Benefits Solutions are frameworks, services, or programs designed to deliver consistent value across changing needs—often by combining planning, responsible procurement, and ongoing stewardship. Instead of treating “benefit” as a one-time outcome, these solutions focus on continuity: reducing service interruptions, managing operational risk, and aligning cost structures with durable performance. For decision-makers, the practical question becomes: Which model, supplier approach, and cost structure will sustain benefits over the long horizon?
In the sections below, you’ll find an expert perspective on what lifetime-oriented benefits usually include, how organizations evaluate them, and what requirements typically determine whether expectations match reality. The discussion blends market-relevant considerations without relying on exaggerated claims, and it emphasizes evaluation methods you can apply immediately.
In many industries, the phrase “lifetime” does not imply an unlimited guarantee. Rather, it generally indicates a good intent—a commitment to provide value over an extended period through structured design, scheduled maintenance, support pathways, and governance. Whether the context is healthcare navigation, home services, employee benefits, vendor-managed operations, or infrastructure stewardship, the principle remains similar: the system should remain usable, serviceable, and financially predictable as conditions evolve.
From an industry standpoint, “lifetime” approaches tend to be grounded in three practical drivers:
To keep this guide professional and evidence-led, note that different countries and sectors define service obligations differently, and “lifetime” language is often regulated by consumer protection rules and unfair or deceptive practices laws. When evaluating any provider’s terms, the decisive factor is usually the contract language, service levels, and documented process—not marketing phrasing.
Another practical background point: lifetime solutions are frequently designed around the realities of how organizations operate. Most organizations experience changes—new teams, reorganizations, new facilities, upgrades, changing regulatory environments, seasonal fluctuations, changing procurement policies, and evolving internal standards. A lifetime-oriented approach aims to stay robust despite those changes, typically through governance mechanisms, defined service scopes, and repeatable processes.
In short, “lifetime” in benefits planning often means: “We will keep the service meaningful and manageable across the foreseeable life of the underlying asset, relationship, or operational cycle.” That definition is more useful—and more verifiable—than simply “forever.”
Industry experts typically evaluate lifetime-oriented solutions using an inverted approach: start with the outcomes and risk controls, then work backward into cost structure and operational delivery. Instead of asking “How cheap is it?” first, the better approach is “What will still work when things change?”
Because lifetime solutions operate across multiple years (or multiple program cycles), evaluation must also consider organizational maturity and service continuity. Even a well-designed offering can fail if the contract is unclear, the supplier’s processes are immature, or the organization cannot meet required conditions (like maintenance compliance or documentation standards).
Ask what “benefits” concretely mean. In many service and operations contexts, benefits are reflected in reduced incidents, faster issue resolution, improved uptime, higher compliance consistency, better patient/consumer navigation, fewer escalations, or smoother transitions when circumstances change (e.g., staff turnover or seasonal demand).
When evaluating Lifetime Benefits Solutions, look for:
A helpful evaluation technique is to map “benefit” into a set of operational behaviors. For example, “predictable outcomes” often requires consistent intake processes, triage rules, documented response times, and scheduled maintenance. If a supplier cannot describe those behaviors in practical terms, “lifetime benefits” can become a vague promise.
Another nuance: outcomes must be measurable, but measurement can be staged. Some benefits (like reduced service disruptions) can be measured directly through incident frequency. Others (like improved user navigation) require process KPIs (time-to-guidance, completion rates, documentation quality) before linking to longer-term effects.
A “lifetime” promise can only be credible if the supplier can operationalize it. Supplier maturity often shows up as consistent process design, clear ownership, supply chain robustness, and the ability to sustain service quality through change.
Consider questions such as:
Supplier maturity also shows in how they handle edge cases. Lifetime programs inevitably face exceptions: unusual usage, partial compliance, delayed reporting, supply shortages, temporary service disruptions, and emergencies. Mature suppliers tend to have documented decision rules, defined contingency actions, and clear communication protocols.
It’s also wise to evaluate whether the supplier’s internal structure supports the “lifetime” claim. For instance, if the program requires periodic review meetings, who owns them? If it requires evidence submission, do they provide templates and guidance? If it depends on a supply chain, how does the supplier ensure parts continuity or plan substitutions?
Where possible, request operational artifacts: service journey diagrams, sample escalation tickets, sample reporting dashboards, maintenance checklists, and example closure notes. The presence of those artifacts is often more informative than a sales narrative.
Even when an offering is positioned as a lifetime solution, the most responsible evaluation compares total cost of ownership. This includes expected recurring fees, service visits, replacement intervals, administrative overhead, and the financial impact of downtime, delays, or noncompliance disputes.
Because you referenced “price information” and “supplier details” in your instructions, the responsible approach is to treat those as inputs to your evaluation rather than fixed universal numbers. Any disclosed price should be considered in context: the scope of coverage, service frequency, defined duration (or conditions for duration), and the boundaries of what “covered” actually means.
Practical rule: If a supplier quote looks low, verify whether it shifts costs into excluded categories (e.g., emergency work, component replacement, labor-only coverage, transport fees, overtime rates, special scheduling charges, diagnostic fees, or documentation fees). Conversely, a higher price can still be rational if it includes broader coverage, stronger service response, and transparent reporting.
But cost evaluation shouldn’t stop at “what’s included.” Lifetime solutions must also consider how costs evolve. Over multi-year horizons, cost predictability depends on:
From a procurement perspective, the top practice is to compare equivalent scope offerings side by side. If scope differs, “low price” often becomes misleading. You can handle this by building a scope matrix that ties each “included benefit” to explicit contractual language and category-level pricing.
Another cost issue is friction cost. Even if the direct service cost appears comparable, a supplier with slower resolution or weaker documentation can create internal overhead: additional staff time, more escalations, delays in compliance reporting, and repeated training for new staff. Lifetime programs should therefore account for the cost of administration—time spent logging requests, collecting evidence, coordinating approvals, and managing renewals.
Lifetime benefits frequently depend on conditions. Typical requirements include adherence to maintenance schedules, use of specified parts or procedures, timely reporting of issues, compliance with documented usage guidelines, and participation in periodic program reviews.
From an objective perspective, these conditions protect both parties: the supplier manages quality risk, and the customer avoids coverage disputes. The top practice is to align your internal processes with the provider’s requirements from day one.
Governance isn’t just administrative; it determines whether the program remains coherent over time. A well-governed lifetime solution often includes:
When evaluating the contract, watch for clauses that can silently break lifetime value. For example: short claim windows, unclear definitions of “covered failure,” broad exclusions, insufficient process detail, or ambiguous renewal mechanisms that allow unilateral changes. These clauses can convert a “lifetime” concept into a series of annual decisions.
It’s also worth verifying how the supplier defines “lifetime” relative to the underlying asset or relationship. Some programs tie lifetime value to the equipment’s service life; others tie it to the contract term; others tie it to compliance with maintenance requirements. Clarity matters because it directly affects whether benefits persist through upgrades, ownership transfers, or system replacements.
Though the term appears in many sectors, it often clusters around long-horizon needs:
Across these contexts, the “lifetime” concept succeeds when it blends process reliability with transparent obligations. In practice, that often means the supplier can answer basic questions like: What happens when something goes wrong? What documentation proves coverage? How are upgrades handled? How do costs remain predictable? How does the supplier maintain service quality when staffing or technology changes?
Lifetime value also depends on the customer’s operational alignment. For example, property stewardship requires property owners to follow maintenance schedules. Equipment support might require scheduled inspections. Employee benefits require timely enrollment and correct documentation. Coordination services require data inputs at the right times. If internal responsibilities are neglected, lifetime promises can become hard to use—even when they’re technically offered.
When organizations discuss good outcomes, credible sources usually come from:
For example, the Federal Trade Commission (FTC) in the United States provides guidance on warranties and refund/disclosure practices, which can help frame how “lifetime” language should be interpreted in consumer contexts. Similarly, many jurisdictions have official consumer protection agencies that evaluate misleading warranty claims.
You can use these sources to validate how “lifetime” commitments are expected to be disclosed and maintained—particularly regarding clarity, not just promise. What matters is not that a supplier “uses the word lifetime,” but that the supplier’s commitments and limitations are communicated clearly enough that consumers can understand what they are buying.
Note: This guide avoids unverified performance statistics. If you need benchmarking numbers for a specific sector (healthcare coordination, equipment support, property services, or managed operations), the best approach is to obtain the relevant report for that exact market segment and interpret it through your organization’s specific context.
One more best practice is to distinguish between claims about benefits and evidence about process capability. Many companies can make broad outcomes claims. Mature providers often have evidence for how their process reduces failure rates, improves turnaround times, or strengthens compliance documentation. When evidence exists, it tends to be operational (process metrics, audit trails, service logs) rather than purely marketing statements.
The table below rephrases supplementary “additional important information” as a structured comparison of typical solution models and the conditions that often determine whether benefits continue as expected. (No external links are included, per your request.)
| Evaluation Dimension | What “Lifetime Benefits Solutions” Should Cover | Common Conditions/Requirements | Decision Signal (What to Verify) |
|---|---|---|---|
| Coverage scope | Defined categories of support across the long term | Inclusions must be explicit; exclusions stated clearly | You can summarize the scope in 5–7 bullet points without assumptions |
| Service continuity | Processes that sustain support through transitions | Planned maintenance or periodic check-ins | There is a named escalation path and a documented response expectation |
| Supplier responsibility | Accountable ownership for ongoing stewardship | Compliance with supplier workflows and reporting rules | They provide a governance model: who does what, when |
| Cost predictability | Clear total cost components and time horizons | Rates may be updated; terms must state how | Pricing is broken down by category (labor, parts, admin, emergencies) |
| Replacement and upgrades | A plan for lifecycle components | Use of approved components; scheduling windows | There is a stated cadence and a process for substitutions |
| Quality assurance | Consistency checks and documentation | Audit trails; acceptance criteria | You receive periodic reports or evidence of service quality |
| Dispute handling | Fair resolution workflow | Defined claims process and time limits | There is a written claims/complaints procedure |
While the comparison table covers core evaluation dimensions, lifetime-oriented solutions often live or die on details that don’t fit neatly into a single row. The following decision signals can help you spot long-term weakness early.
If you can identify these signals in supplier materials, you’re better positioned to predict whether the service will remain usable when the contract is no longer fresh and when “normal usage” eventually changes.
Use this structured approach to evaluate suppliers and align internal readiness. It is intentionally pragmatic and designed for procurement, operations, customer success, compliance, and finance teams. Because lifetime solutions affect long-term cost and risk, it’s best to involve stakeholders early—not after you have a signed agreement.
Defining outcomes early protects you from “scope drift.” Scope drift happens when the organization’s needs change but the contract’s practical delivery model doesn’t. If you define outcomes and time horizons, you can later test whether the supplier’s delivery plan continues to serve those outcomes.
A strong scope checklist typically includes both scope breadth (what categories are covered) and scope depth (what actions are required for those categories). For example, “repairs” might appear broad, but depth determines whether the supplier handles diagnostics, parts sourcing, scheduling, and closure evidence.
Category-level transparency does more than show cost—it reveals how the supplier expects the service to be delivered. If most costs are buried inside exclusions or “additional services,” the “lifetime benefits” value can shrink under realistic conditions.
When comparing multiple providers, ensure that pricing is normalized to the same scope assumptions. If one supplier includes routine checks and another doesn’t, their base prices are not comparable.
Operational capability should be evaluated through evidence, not just descriptions. Sample documents help you verify whether the supplier’s process is mature enough for long-term consistency. For example, if they provide only a generic “service request” form but can’t explain closure evidence, you may later face disputes about whether the service was performed according to contract requirements.
This step is often where lifetime value is made or lost. If your internal teams can’t support required processes, the supplier’s “lifetime” benefits may effectively become hard to use. Aligning internal responsibilities early prevents coverage disputes and reduces the need for emergency work.
To make alignment concrete, consider creating an internal “program operating model” document that mirrors the supplier’s required workflow. For example: intake, triage, scheduling, evidence logging, escalation triggers, and closure steps.
Pilots are not only about performance—they are about process compatibility. A supplier can respond quickly, but if their documentation doesn’t satisfy your internal audit needs, the program may still fail long-term. Use pilots to test both customer experience and evidence adequacy.
A risk-lens contract review should identify not only what is promised but what can be withheld. Look for broad exclusions, ambiguous trigger definitions, overly narrow claim processes, and requirements that are difficult to satisfy. Also verify how the supplier communicates and documents service delivery so that evidence exists if disputes arise.
Very lifetime-oriented benefit programs include conditions. Preparing early reduces disputes and improves continuity. Typical conditions include:
If you ever encounter language that’s vague—especially around “lifetime benefits solutions,” coverage duration, replacement eligibility, or what constitutes compliance—seek clarification in writing before committing. Clarification in writing matters because future disputes often turn on documented interpretation, not oral assurances.
How to prepare operationally:
These preparations may seem administrative, but they are the foundation of lifetime value because they keep eligibility and evidence intact over time.
You mentioned supplier details in your instructions. In credible lifetime-oriented offerings, supplier quality is often evident through more than promises—it’s visible in clarity, documentation, ownership, and lifecycle planning.
You should expect suppliers to provide:
When comparing multiple providers, consider asking for a sample “service journey” document: how a request starts, what happens during assessment, how approvals work, what the supplier does before scheduling, how closure is documented, and how reporting is delivered. The clarity of that journey often predicts customer experience far more reliably than promotional language.
Also ask about continuity of knowledge. Over multiple years, a supplier may encounter new staff, new technology, or changes in internal processes. Mature suppliers maintain continuity through standardized documentation, knowledge bases, and periodic reviews with the customer. If documentation is inconsistent or tribal knowledge is required, long-term value is at risk.
Finally, supplier details should include communication norms. Do they respond with status updates? Are escalations communicated promptly? Is there a single point of contact? Does the supplier provide a consistent escalation template and evidence package? These operational details affect whether “lifetime” remains usable across real-life events.
Although this guide does not assume a specific price figure, price information should be evaluated as a system rather than a number. Key pricing evaluation dimensions include:
From an objective procurement standpoint, the top practice is to compare equivalent scope. If one offering includes routine maintenance inspections and another does not, comparing “price per year” can produce misleading conclusions.
One practical tool is a “cost scenario” worksheet. Instead of comparing pricing only at a hypothetical baseline, create scenarios that represent reality:
For each scenario, estimate direct costs and indirect costs (administrative overhead and schedule delays). Lifetime value emerges when the supplier’s pricing and processes reduce total cost across these scenarios rather than only under ideal assumptions.
Also consider whether the supplier can provide a “total cost estimate” grounded in your expected usage. If they can’t, they may not understand the operational drivers that determine long-term cost. In that case, you may need to build a cost model yourself using scope definitions, service frequency, and historical incident assumptions.
They are long-horizon frameworks—often service plans, coordination models, or stewardship programs—designed to keep value consistent over an extended period. They typically focus on continuity, risk management, and clear conditions that must be met for ongoing benefits.
Not necessarily. In some contexts, “lifetime” language means a good commitment with defined conditions, scope boundaries, and claim procedures. The correct interpretation depends on the contract terms and program rules, including what “lifetime” is tied to (asset life, program period, or customer relationship) and what conditions apply to eligibility.
Prioritize definitions of coverage scope, exclusions, service response or escalation workflows, claim submission rules, timelines, maintenance requirements, pricing adjustment mechanics, reporting cadence, and dispute handling procedures. Also look for transition and continuity terms—how service remains stable if staffing or parts supply changes.
Compare using an equivalent-scope checklist: separate inclusions, recurring requirements, replacement/upgrade handling, documentation/reporting expectations, and emergency or out-of-scope charges. Then evaluate operational maturity and governance (who owns what, when, and how evidence is maintained).
No. While price matters, total cost visibility and risk-adjusted continuity usually matter more over the long term. A slightly higher price can be rational if it reduces downtime, clarifies responsibilities, lowers the chance of costly disputes, and provides better documentation quality.
Common conditions include adherence to maintenance schedules, timely reporting, compliance with approved procedures or components, evidence requirements, and respect for claim deadlines. Also check whether continued eligibility depends on participation in governance activities (reviews, training refreshers, or periodic program checks).
Consumer protection agencies and warranty guidance from official bodies are useful for understanding disclosure expectations. For the United States, the FTC provides guidance that can help frame what counts as clear and not misleading disclosure. For other regions, consult local consumer protection authorities and sector regulators.
Yes, but the results depend on discipline and documentation. Without a supplier, you must build your own governance, maintenance routines, evidence capture, escalation workflow, and lifecycle replacement planning. A supplier can reduce operational overhead if their processes are strong and clearly defined, but internal accountability still matters.
In mature lifetime programs, obsolescence handling is defined through approved substitutions, lifecycle replacement cadence, and upgrade processes. Verify how substitutions are approved, whether performance requirements are maintained, and whether any additional costs apply.
Ask for evidence: service logs templates, reporting examples across time, references that demonstrate multi-year delivery, sample escalation cases, and onboarding materials that show how knowledge is transferred and refreshed. Also check whether the supplier has governance and audit routines that continue regardless of turnover.
Lifetime Benefits Solutions succeed when they turn good intent into operational reality—through explicit scope, credible supplier capabilities, transparent pricing, and enforceable conditions that both sides understand. By using a scope checklist, verifying supplier maturity, and evaluating total cost visibility rather than headline figures, you can choose a solution that protects continuity and supports consistent outcomes over time.
To apply the concept immediately, focus on three practical outcomes: (1) can you clearly state what “covered benefits” means in operational terms, (2) can you show how eligibility is maintained through real conditions like maintenance and evidence, and (3) can you model total cost and continuity risk across realistic scenarios rather than only an ideal baseline.
If you share your specific sector (e.g., property stewardship, employee benefits, equipment service, or coordination services) and the type of “price information” you have in mind, the evaluation framework in this guide can be tailored into a more precise supplier comparison and requirements checklist.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
Pet Insurance Essentials: Coverage, Costs, and Resources Explained
In recent years, pet ownership has seen a significant surge. Pets, whether they're dogs, cats, birds, or other animals, have increasingly become integral parts of our families. With this growing bond, there is a rising awareness of the importance of pet health and well-being. Just as health insurance is crucial for humans, pet insurance is becoming an essential consideration for pet owners. This article aims to provide a comprehensive understanding of pet insurance, covering its importance, types of coverage, associated costs, and valuable resources to help you make an informed decision.
Colbate Explained: Uses, Sourcing, and Top Practices
This guide explains Colbate from a practical industry viewpoint, covering what it is, how suppliers typically handle it, and what buyers should verify before purchase. It also summarizes objective background on related terminology, common application considerations, and due-diligence steps. Readers will find a comparison table, requirements, and targeted FAQs to support confident sourcing decisions.
Strategies for Financial Security and Legacy Planning
Life insurance isn't just about what happens after you pass—it's a strategic tool in a comprehensive plan for your financial security and estate planning.
Navigating Insurance Costs for Seniors: Essential Tips and Advice
As we age, healthcare costs and the complexity of managing them can become increasingly burdensome. For many seniors, navigating insurance costs is a crucial aspect of ensuring financial stability and maintaining health. This guide aims to provide you with essential tips and advice on how to manage and potentially reduce these costs effectively.
Discovering Dunlop Brooklin Footwear
This article delves into Dunlop Brooklin, a prominent name in the footwear industry known for its exceptional quality and innovation. Dunlop is recognized for its wide-ranging collection of shoes designed to meet diverse customer needs, from casual wear to professional attire. This guide provides an in-depth analysis of Dunlop Brooklin and its offerings, revealing why it stands out in the market.
Your Guide to Understanding Car Insurance Coverage
Navigating car insurance can be puzzling. Fortunately, this guide illuminates coverage types and choosing the right provider.